
Internal Revenue Service (IRS) · United States (federal)
Schedule 8812 (Form 1040): Credits for Qualifying Children and Other Dependents
Current revision: Tax year 2025 (checked on irs.gov, Oct 28, 2026)
Fill in IRS Schedule 8812 (Form 1040) for the $2,200 child tax credit, $500 credit for other dependents and the refundable additional child tax credit.
Filling needs no account. Downloading, printing or sending the completed form needs a free account — 3 downloads a month, no watermark.
Page reviewed
Form
Schedule 8812 (Form 1040)
- Issued by
- Internal Revenue Service (IRS)
- Applies in
- United States (federal)
- Edition
- Tax year 2025
Official source
PDFBetter is not affiliated with, endorsed by or acting for Internal Revenue Service (IRS). We open the form from irs.gov, and you fill it in our editor. Check the issuer's instructions before you file.
What it is
What Form Schedule 8812 (Form 1040) is for
Schedule 8812 figures the child tax credit, the credit for other dependents and the refundable additional child tax credit. For tax year 2025 the child tax credit is up to $2,200 per qualifying child and the refundable part up to $1,700; the 2026 draft instructions show the same amounts. The PDF on irs.gov is the 2025 edition, and starting with 2025 you need a valid SSN to claim the child tax credit. The IRS can't issue refunds on returns claiming the additional child tax credit before mid-February 2027.
Schedule 8812 (Form 1040) deadlines, 2027 filing season
File Schedule 8812 with your 2026 return Source: irs.gov
Extended 2026 return with Schedule 8812 Source: irs.gov
Dates already move past weekends and DC holidays, as the IRS rule says. Checked against irs.gov on October 28, 2026. See the full 2027 tax calendar.
Fill it here
From irs.gov to your filled copy
- 1
Fetched from irs.gov
The agency's own, current PDF — not a retyped copy.
- 2
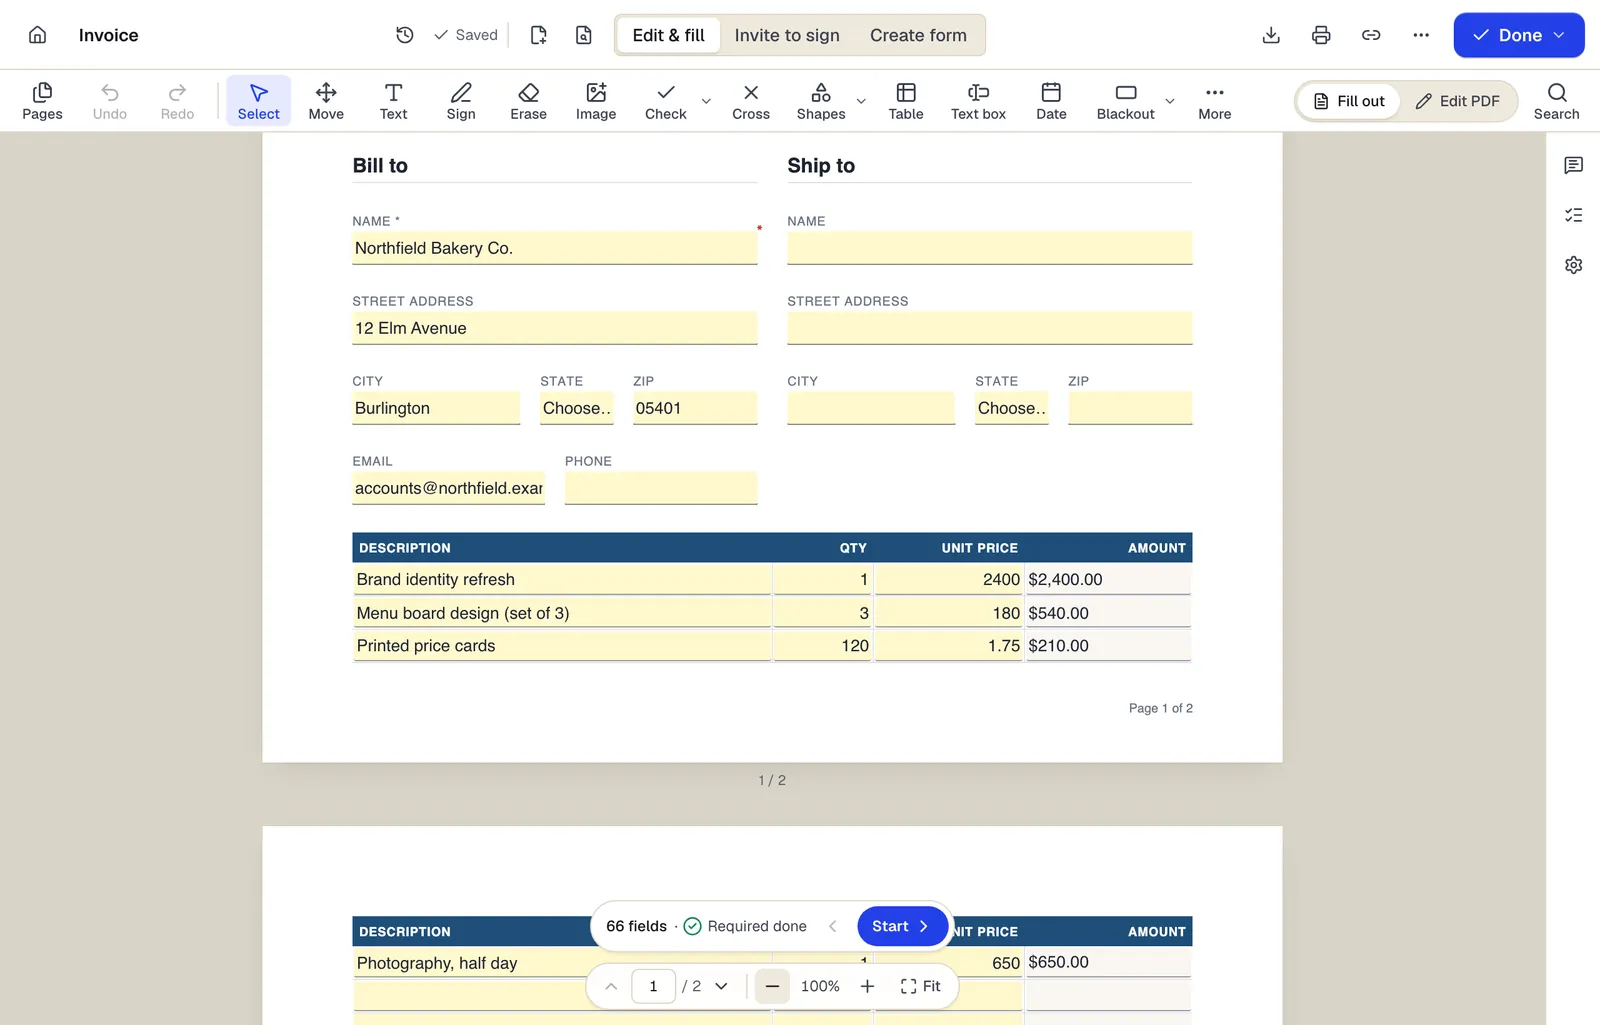
Opens in the editor
Fillable fields work as they are; on a flat page you type with text boxes.
- 3
Your filled copy
Download, print, sign or send it — the original stays untouched.
Who files it
- Parents with a qualifying child under 17 who has a valid SSN
- Taxpayers with other dependents, such as older children or relatives
- Families who may get part of the credit as a refund
- Bona fide residents of Puerto Rico claiming the additional child tax credit
What you need
- Your AGI from Form 1040, line 11a
- SSNs for you, your spouse and each child
- Number of qualifying children under 17 with a valid SSN, and number of other dependents
- Earned income (wages, net self-employment income)
- Forms W-2 if you have three or more qualifying children (for Part II-B)
Line by line
How to fill out Form Schedule 8812 (Form 1040)
- 1
Lines 1–3 — income
Enter your AGI from Form 1040, line 11a, plus any excluded foreign or Puerto Rico income on lines 2a–2c. Line 3 is the total.
- 2
Lines 4–8 — credit before phaseout
Enter the number of qualifying children under 17 with the required SSN on line 4 (times $2,200) and the number of other dependents on line 6 (times $500). Line 8 is the total.
- 3
Lines 9–12 — phaseout
Line 9 is $400,000 if married filing jointly or $200,000 for everyone else. The credit drops by 5% of income above that, in $1,000 steps.
- 4
Lines 13–14 — tax limit
Use Credit Limit Worksheet A for line 13. Line 14 is your child tax credit and credit for other dependents; enter it on Form 1040, line 19.
- 5
Part II-A — additional child tax credit
If line 12 is more than line 14, figure the refundable part: up to $1,700 per qualifying child, limited to 15% of earned income over $2,500 (line 20).
- 6
Parts II-B and II-C
Filers with three or more qualifying children can use Part II-B (based on Social Security and Medicare taxes withheld) if it gives more. Line 27 goes to Form 1040, line 28.
Common Schedule 8812 (Form 1040) mistakes
- Counting a child who turned 17 by the end of the year; they can only count as an other dependent.
- Claiming the child tax credit without a valid SSN for the child issued before the return's due date.
- Claiming the credit when neither spouse has a valid SSN (on a joint return, one valid SSN is enough).
- Skipping Form 8862 after a prior disallowance of the credit for a reason other than a math or clerical error.
Where to send it
Attach Schedule 8812 to your Form 1040, 1040-SR or 1040-NR and file by April 15, 2027 for tax year 2026 (October 15, 2027 with an extension). Paper return addresses: https://www.irs.gov/filing/where-to-file-paper-tax-returns-with-or-without-a-payment. A paper return needs a handwritten signature.
Filing rules change. Confirm the address or portal on irs.gov before you send.
Form Schedule 8812 (Form 1040): questions people ask
Which year is this Schedule 8812 for?
The PDF on irs.gov today is for tax year 2025. A draft of the 2026 instructions is on irs.gov/draft-tax-forms; the final 2026 schedule usually appears in December or January.
What are the amounts for 2026?
The 2026 draft instructions show a maximum child tax credit of $2,200 per qualifying child and a maximum additional child tax credit of $1,700, the same as 2025.
My child has an ITIN, not an SSN. Can I claim anything?
Not the child tax credit, which needs a valid SSN for the child. You may be able to claim the $500 credit for other dependents if the child has a TIN issued by the due date of the return.
Why is my refund late?
The IRS can't issue refunds before mid-February for returns that properly claim the additional child tax credit, and the hold applies to the entire refund. For 2026 returns that's mid-February 2027.
Do both parents get the credit after a divorce?
No. Only the parent who claims the child as a dependent can claim the credit for that child. The instructions explain the special rules for divorced or separated parents.